How to Download Bhoomi RTC / Pahani in Karnataka
You can get the Bhoomi RTC / Pahani online easily via mypatta without visiting the Sub-Registrar office.
- Open mypatta and log in or sign up if needed.
- Go to property documents, ensure “Karnataka” is selected as the state, then tap the “Bhoomi RTC / Pahani” icon.
- Enter required information.
- Tap “Search”
- Once Bhoomi RTC / Pahani is available to download, tap “View Document”. You can now save or share or download this document in PDF on your device.
What Legal Value Does a Bhoomi RTC Have in Karnataka?
A Bhoomi RTC has statutory and evidentiary value as part of Karnataka’s official Record of Rights system. It is not merely an informal summary of land details.
Section 127 of the Karnataka Land Revenue Act, 1964 provides for the preparation of a Record of Rights for every village. The record may include the names of holders, occupants, owners, mortgagees, landlords and tenants, together with the nature and extent of their respective interests, attached liabilities and revenue particulars.
Section 133 further states that an entry in the Record of Rights, as well as a certified mutation entry, is presumed to be true until the contrary is proved or a new entry is lawfully substituted. This means that an RTC entry carries an initial presumption of correctness and cannot be casually ignored.
However, the presumption is rebuttable. It may be displaced by:
- a registered deed showing a different legal position;
- an earlier or subsequent certified mutation entry;
- a civil court decree;
- survey and subdivision records;
- succession or partition documents; or
- evidence showing that the entry is outdated, mistaken or fraudulently obtained.
The RTC is therefore valuable for identifying the position recorded by the Revenue Department. Its legal weight increases when the entry is current, supported by a certified mutation and consistent with the underlying title documents.
For a buyer, the RTC can help answer several preliminary questions: Is the seller’s name recorded? Does the survey number exist? What extent is shown? Are there other holders, tenants or cultivators? Has a recent change been entered? Are there remarks suggesting a dispute or restriction?
It does not, however, finally decide a contested title. Where rival parties claim ownership, the title dispute may require determination by a competent civil court.
Can a Karnataka RTC Be Used as Ownership Proof?
A Karnataka RTC can be used as supporting evidence of ownership, possession or an interest recorded against agricultural land, but it should not ordinarily be treated as conclusive ownership proof by itself.
The RTC may show that a person is entered as the holder or occupant of a particular survey parcel. This is relevant because the entry is part of an official statutory record and carries a rebuttable presumption of correctness.
However, ownership must ultimately be traced to a legally recognised source, such as:
- a registered sale deed;
- a gift, settlement, release or partition deed;
- inheritance supported by succession records;
- a government grant;
- a court decree; or
- another legally valid instrument creating or transferring rights.
The Supreme Court has repeatedly clarified that mutation and revenue entries are primarily maintained for fiscal and administrative purposes and do not, by themselves, create or extinguish title. In its December 2025 decision in Tarachandra, the Court reiterated that a mutation entry does not independently confer title and that disputed rights must be resolved in appropriate proceedings.
The correct legal position is therefore balanced:
- The RTC is not irrelevant or legally meaningless.
- Its entries carry evidentiary value and a statutory presumption.
- It may support continuity of possession and the recorded revenue position.
- It does not cure a defective deed or establish that the transferor had a complete title.
- It cannot replace examination of the title chain.
For example, where the seller holds a registered sale deed, the earlier deeds establish the seller’s predecessor’s rights, the corresponding mutation has been certified and the latest RTC reflects the seller’s name and correct extent, the RTC strengthens the ownership claim.
The position is weaker where the seller relies only on an RTC entry but cannot produce the deed, succession record, grant or other document explaining how the right was acquired.
How to Compare the RTC With the Registered Deed and Mutation Records
The registered deed, mutation record and RTC perform different but connected functions. They should be examined together rather than treated as substitutes for one another.
| Record | Primary due-diligence purpose | Important comparison points |
|---|
| Registered deed | Shows the transaction or instrument through which rights were transferred | Parties, execution date, registration details, survey number, hissa, extent, boundaries and nature of rights transferred |
| Mutation record | Shows the process through which the reported change was considered and entered in the revenue system | Mutation number, source document, affected survey parcel, transferor, transferee, extent, objections and certification status |
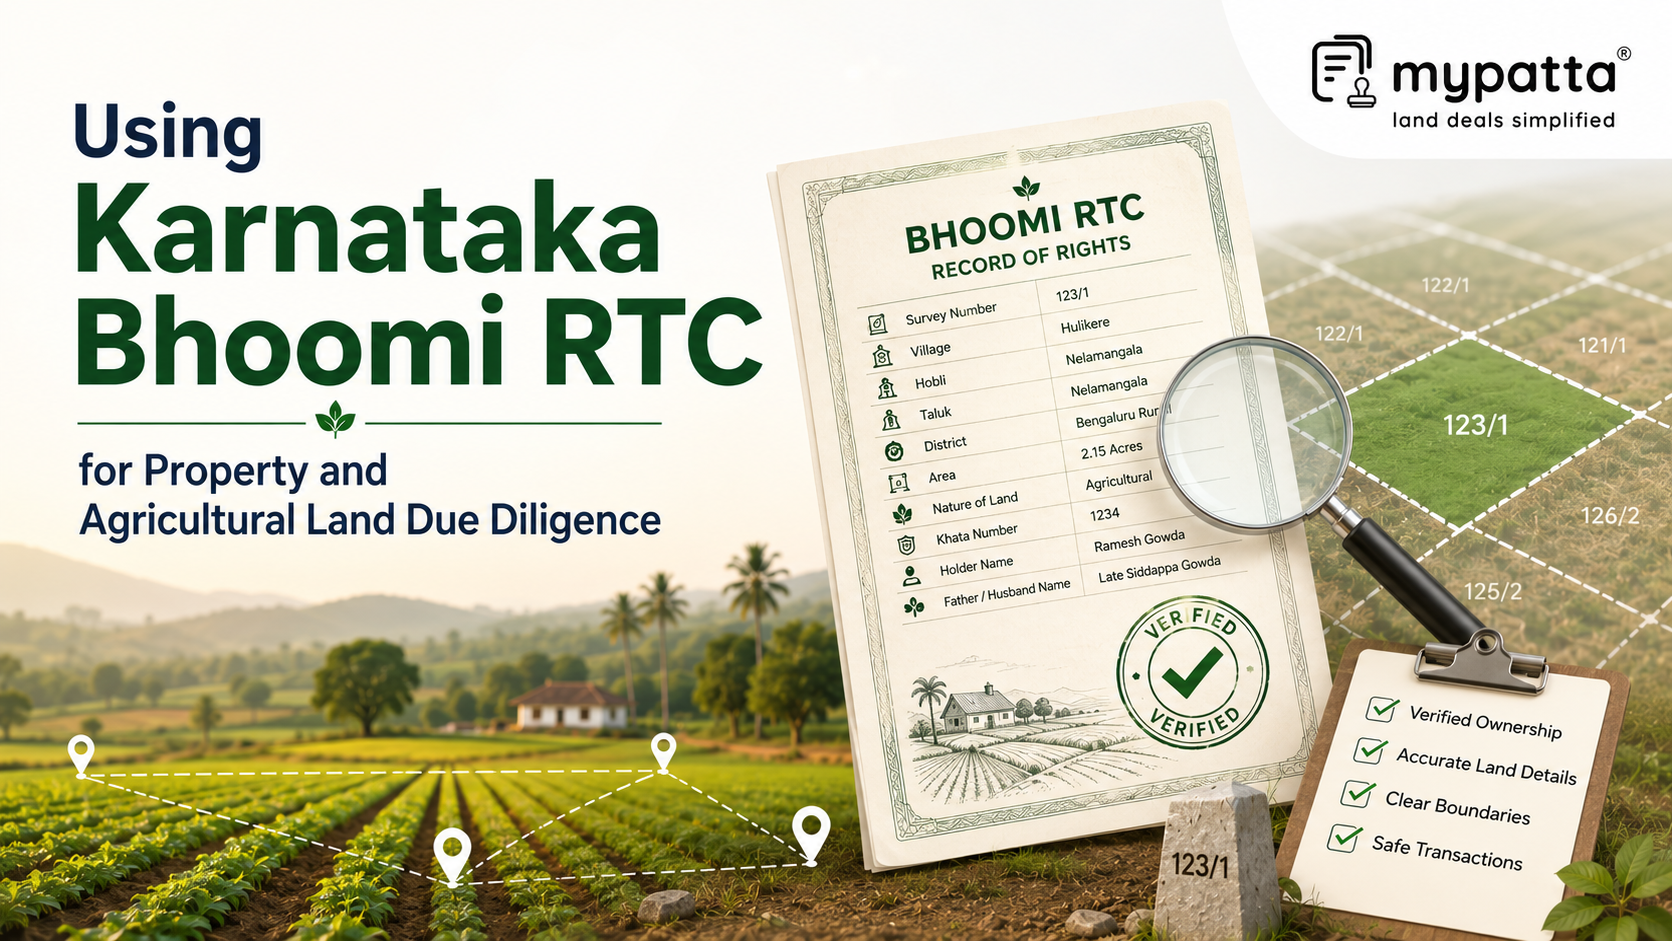
| Bhoomi RTC | Shows the resulting or current revenue-record position | Recorded holder, share, survey and subdivision, extent, cultivation, tenancy, classification and remarks |
The comparison should begin with the identity of the property. The district, taluk, hobli, village, survey number, surnoc, hissa and subdivision in the deed must correspond with the RTC.
The extent also requires careful comparison. The deed may transfer only a part of a larger survey number, while the RTC may show the total parent extent. In a jointly held property, the RTC may reflect a fractional share rather than a physically divided portion.
The buyer should then identify the mutation entry connected with the deed or succession event. Sections 128 and 129 of the Karnataka Land Revenue Act provide for reporting acquisitions of rights, entering them in the Register of Mutations, notifying interested persons, recording objections and certifying the mutation before transferring it into the Record of Rights.
The Karnataka Revenue Department similarly explains that changes in an RTC, other than crop entries, are carried through mutation. These may arise from registered instruments such as sale, gift and partition deeds or from events such as inheritance.
During the comparison, check whether:
- the mutation refers to the same deed number and registration date;
- the transferor and transferee match the deed;
- the correct survey number and hissa were affected;
- the transferred extent matches the deed schedule;
- objections were raised or a dispute was recorded;
- the mutation was approved and certified; and
- the latest RTC reflects the certified change.
A deed followed by a pending or rejected mutation requires explanation. At the same time, a completed mutation cannot validate a deed executed by a person who had no transferable title.
What RTC Entries Should a Land Buyer Examine Carefully?
A land buyer should examine the RTC as a complete record. Focusing only on whether the seller’s name appears can result in serious issues being overlooked.
Recorded holder and share
Where more than one person is named, check the extent or share recorded against each person. The seller may be entitled to only an undivided share and may not have the authority to transfer the entire parcel.
A buyer should also verify the father’s or predecessor’s name, particularly where several family members have similar names.
Survey number, surnoc and hissa
The main survey number may contain several subdivisions. The deed and RTC must refer to the same hissa or subdivided parcel.
A mismatch may indicate that:
- the deed describes a portion that has not been formally subdivided;
- the RTC relates to the parent survey;
- the wrong parcel has been retrieved; or
- phodi or subdivision proceedings remain incomplete.
Extent and land description
The total extent, cultivable area, uncultivable portion and individual share should be distinguished.
The recorded extent should also be compared with the deed schedule and survey records. A difference may arise from an old measurement, subdivision, road acquisition, government deduction, encroachment or clerical error.
Nature of the recorded interest
The RTC may separately refer to a holder, occupant, tenant, mortgagee or cultivator. The buyer must identify the capacity in which each person is entered.
The presence of another cultivator or tenant should not automatically be dismissed. It may indicate an existing tenancy, possession arrangement or competing factual claim requiring further investigation.
Mutation references
Check the mutation number, date and basis of every significant change in the ownership-related entries.
A recent entry should be traced to the deed, succession document or order that caused it. Pending, disputed, rejected or unusually delayed mutations require closer scrutiny.
Land classification and use
The RTC may indicate whether the land is agricultural, irrigated, dry, government-related, granted or subject to another recorded classification.
The current physical use of the land should be consistent with its legal classification. Where agricultural land is being used or marketed for residential, commercial or industrial purposes, separate conversion and planning approvals must be verified.
Remarks and liabilities
Any remark concerning a mortgage, dispute, court proceeding, government interest, restriction, acquisition or correction should be examined through the underlying order or proceeding.
The official Karnataka portal separately allows citizens to view RTCs, mutation records, dispute cases, mutation pendency and several survey documents. These services can help identify issues that may not be fully explained by the face of the RTC.
What Can a Bhoomi RTC Not Verify by Itself?
A Bhoomi RTC cannot provide complete property due diligence because it is designed primarily as a revenue record.
By itself, it cannot conclusively verify:
- the complete title chain of the seller;
- the legal validity of the registered deed;
- whether the transferor had authority to transfer the entire property;
- later registered sales, gifts, mortgages or releases;
- unregistered agreements or private family arrangements;
- pending civil, criminal or tribunal proceedings;
- exact physical boundaries on the ground;
- encroachments or loss of access;
- approved non-agricultural conversion;
- zoning, planning or building permissions;
- acquisition notifications or infrastructure reservations;
- compliance with conditions attached to granted land; or
- the absence of claims by legal heirs, co-owners or creditors.
A clean RTC does not necessarily mean that the land is free from encumbrances. A mortgage or later registered document may have to be identified through registration and encumbrance searches.
Similarly, the RTC does not establish that the land physically occupied by the seller is the same parcel described in the deed. Exact identity and boundaries require examination of survey sketches, subdivision records and, where necessary, an official measurement.
The RTC also cannot determine whether a deed is forged, void, cancelled, obtained through fraud or executed without authority. These questions require examination of the original transaction, registration records and any relevant court proceedings.
Which Documents Should Be Checked Along With the RTC?
A sound due-diligence exercise should connect the seller’s legal title, the registration history, the revenue entries and the physical identity of the land.
The following documents should ordinarily be checked:
- Registered title deed: The seller’s sale, gift, partition, release or settlement deed.
- Mother deed and link documents: Earlier deeds establishing a continuous title chain.
- Certified mutation records: The mutation connected with each material transfer, inheritance or partition.
- Encumbrance Certificate and registered-document search: Later transfers, mortgages, releases and registered charges.
- Akarband and survey records: Survey number, extent, assessment and parcel particulars.
- Tippan, Atlas, Pakka Book and phodi sketch: Measurements, subdivisions and boundary-related details.
- Village map and access records: Location, adjoining parcels, roads and public features.
- Succession documents: Death certificate, legal-heir records, will, probate or family arrangement, where relevant.
- Grant or saguvali documents: Conditions and restrictions where the land originated through a government grant.
- Conversion order: Permission for lawful non-agricultural use, where applicable.
- Revenue and civil court records: Pending disputes, appeals, injunctions or declaratory proceedings.
- Tax and local-authority records: Relevant where the land has been converted, developed or brought within an urban authority.
The Karnataka Revenue Department’s unified portal currently provides access to present and old RTCs, mutation records, mutation status, dispute information, Akarband, survey documents and revenue maps. These services are useful for collecting the revenue and survey side of the due-diligence record, but they do not replace legal examination of the deeds and title chain.
For agricultural land, the due-diligence conclusion should be based on consistency across all four layers:
- Title: How the seller legally acquired the property.
- Registration: Whether subsequent registered transactions or encumbrances exist.
- Revenue: Whether the mutation and RTC correctly reflect the title documents.
- Survey and possession: Whether the land on the ground matches the recorded parcel.
Why mypatta?
- Trusted by 7 Lakh+ Customers
- 1 Crore+ Documents Delivered
- mypatta Guarantee: Guaranteed delivery or a 100% refund
- 4.8-Star App Rating
Your money is safe with us: Guaranteed delivery or a 100% amount refund.
FAQs
- 1. Is an RTC compulsory when buying agricultural land in Karnataka?+
An RTC is an important due-diligence record because it shows the current revenue position, land particulars and recorded interests. However, it must be checked with the registered deed, mutation history, encumbrance records and survey documents.
- 2. Can a seller transfer land when their name is not shown in the latest RTC?+
The absence of the seller’s name may result from a pending mutation, but the reason must be verified. The seller should establish a valid title through the registered deed or succession documents, and the mutation status should be examined before the transaction proceeds.
- 3. What does it mean if the sale deed and RTC show different extents?+
The difference may arise from joint ownership, subdivision, phodi proceedings, an old measurement or an incorrect revenue entry. The deed, mutation record, Akarband and survey sketch should be compared to identify the correct extent.
Shivangi
Real Estate Content Writer
Shivangi is a real estate content writer with 3+ years of experience helping readers understand property documentation, land records, and legal requirements through clear and actionable content.